X Square Robots
US$0.99 unlocks one Word + one PDF download. The full report is free to read on this page.

X Square Robots: Capital-Rich, Evidence-Poor
An embodied-AI startup that has raised roughly $280M in under three years, claims a $2.8B valuation, and ships wheeled dual-arm robots into schools, hotels and care homes — yet has not publicly demonstrated, to any independent standard, that those robots work without a human in the loop.
| Report status | Coverage date | Company stage | Editorial standard |
|---|---|---|---|
| Premium editorial deep report; evidence-led, vendor-claims separated from verified facts | Evidence gathered 22 September 2026; company events referenced through April 2026 | Fully commercial (reported revenue-generating sales); autonomy unverified | Claims labelled; no demo treated as proof; no shipment treated as deployment; no partnership treated as paid customer |
How to Read This Report
This report is built on a deliberately thin evidence base, and it says so at every turn. X Square Robots is a young company (founded December 2023) operating in a sector where the gap between a funding announcement and a verified capability is routinely enormous. The dossier underpinning this report contains no peer-reviewed papers authored by the company, no independent teardowns, no named-customer confirmations, and no first-hand user reports. What it does contain is a dense cluster of funding coverage, a handful of vendor and reseller product pages, and generic community commentary about Chinese robotics that does not test X Square specifically.
That asymmetry — abundant capital evidence, scarce capability evidence — is itself the central finding. Throughout, every substantive statement is tagged with one of four evidence labels:
| Label | Meaning | Example in this report |
|---|---|---|
| VERIFIED FACT | Regulatory filings, official product documentation, named-customer confirmation, peer-reviewed or primary research, or corroboration across multiple independent sources | The company is Shenzhen-based and founded December 2023 156 |
| COMPANY CLAIM | Stated by X Square or its agents, not independently verified | "Over 80% autonomous completion on real-robot tasks without any post-training" |
| EDITORIAL INFERENCE | Reasoned conclusion drawn from public evidence, explicitly flagged as such | The funding cadence implies a capital strategy prioritising model scale over near-term unit economics |
| UNKNOWN | Not publicly disclosed, or disclosed only in a form that cannot be checked | Task-level autonomy; unit economics; actual paying-customer count |
Three discipline rules govern the whole document. First, a choreographed demo video is never treated as proof of autonomous work. Second, a shipment is never treated as proof of productive deployment. Third, a partnership announcement is never treated as proof of a paid customer. Where the dossier is silent, the report states "Not publicly disclosed" rather than padding with inference dressed as fact.
One structural note: the module placeholders embedded in this report (<!-- module: ... -->) are rendered by the publishing platform with live database content — news, products, papers, media, competitors and so on. The prose around each placeholder is written to stand on its own and to frame what that panel should be read against.
01Executive Overview
X Square Robots is, on the available evidence, a capital-market phenomenon before it is a robotics phenomenon. VERIFIED FACT: The Shenzhen company, formally Variable Robotics Technology Co., was founded in December 2023 and has since raised a reported total of roughly RMB 2 billion (about US$280 million) across as many as ten rounds, including a ~US$100 million round in 2025 and a RMB 1 billion (~US$140 million) Series A++ in January 2026, followed by a Series C 15678. VERIFIED FACT: Multiple independent outlets report a post-Series-C valuation above US$2.8 billion (RMB 20 billion) 68. VERIFIED FACT: Its investor list — Alibaba, ByteDance, Meituan, HongShan (formerly Sequoia China), Xiaomi, IDG, SAIC Financial Services/CICC-SAIC Fund and Lenovo Star — is corroborated across CNBC, PR Newswire, Pulse2, Gasgoo and The Robot Report 15678.
Against that, the capability evidence is startlingly thin. COMPANY CLAIM: X Square develops the WALL family of embodied foundation models — WALL-A (vision-language-action plus world models), the open-sourced WALL-OSS (September 2025), and WALL-B (April 2026, described as a "World Unified Model" architecture) — and sells the Quanta X1 and X2 wheeled dual-arm semi-humanoid robots plus the Artixon hand 2569. COMPANY CLAIM: It reports revenue from sales to schools, hotels and retirement homes, plus household-cleaning bookings and nursing-home deployments 126. UNKNOWN: Whether any of these robots perform their tasks without a human performing or remotely driving them. The only autonomy evidence in the dossier is vendor-sourced: a chief operating officer's statement that robots must "operate and complete complex tasks autonomously," and a vendor-reported figure of "over 80% autonomous completion on real-robot tasks without any post-training" 9. No independent review, teardown or first-hand user report corroborates either.
EDITORIAL INFERENCE: The reconciled autonomy verdict is therefore unknown, not autonomous, not supervised-autonomous, not teleoperated. The absence of independent verification is not evidence of failure — but in a sector where teleoperation is routinely presented as autonomy, it is not evidence of success either. The honest position is that X Square has not yet been tested in public.
The strategic picture that emerges is of a company that has correctly identified the winning narrative of the 2025–2026 robotics cycle — embodied foundation models, open-source distribution, physical-AI positioning — and has raised aggressively against it, while the operational proof of that narrative remains locked inside vendor communications. EDITORIAL INFERENCE: This is a rational capital strategy in a market that rewards model-scale claims, but it leaves the company exposed to the first serious independent evaluation. The gap between a $2.8 billion valuation and an unverified 80% autonomy figure is the single most important thing to watch.
Latest news
- P.A.R.: a robot that draws pixel art by flipping disksOpen-electronics.org·2026-09-20GENERAL
- Kenco opens new innovation lab for warehouse automation testingBiztoc.com·2026-09-14GENERAL
- Kenco opens new innovation lab for warehouse automation testingYahoo Entertainment·2026-09-14GENERAL
- Humanoid robots fight it out in RiyadhBiztoc.com·2026-09-14GENERAL
- Agility Robotics plants its flag in Tesla’s backyardBiztoc.com·2026-07-17GENERAL
02The X Square Robots Story
VERIFIED FACT: X Square Robot is a Shenzhen, China-based embodied-AI robotics company founded in December 2023, formally registered as Variable Robotics Technology Co. 15. The Shenzhen location and 2023 founding are agreed across multiple independent news and commerce sources, and The Robot Report supplies the formal legal name 5. The company is young even by the standards of the current robotics cycle: at the time of this report it is not yet three years old.
VERIFIED FACT: Its funding history is unusually compressed. CNBC reported in September 2025 that Alibaba led a US$100 million investment 1. The Robot Report subsequently reported a US$140 million raise framed around AI foundation models 5. PR Newswire described "four consecutive financing rounds" taking the company past a US$2.8 billion valuation 6, a figure Pulse2 independently reported 8. Gasgoo reported a further "hundreds of millions of yuan" seed-stage-style round 7, and a commerce listing aggregates the funding and investor picture 4. EDITORIAL INFERENCE: The round-count and total vary by outlet and by date — CNBC, The Robot Report, PR Newswire, Pulse2 and Gasgoo overlap but do not agree on a single canonical figure — which is normal for a company raising this fast, but it means the "roughly $280M total" should be read as an order of magnitude, not an audited number.
VERIFIED FACT: The investor roster is the company's most independently corroborated asset. Alibaba, ByteDance, Meituan, HongShan/Sequoia China, Xiaomi, IDG, SAIC Financial Services/CICC-SAIC Fund and Lenovo Star appear across CNBC, PR Newswire, Pulse2, Gasgoo and The Robot Report, and the lists overlap and corroborate one another 15678. EDITORIAL INFERENCE: The presence of both Alibaba and ByteDance — competitors in cloud and AI — alongside Meituan (local services, delivery, eldercare-adjacent) and Xiaomi (consumer hardware and smart home) suggests X Square is being positioned as a strategic asset across several ecosystems at once, not merely a financial bet. That is a strong signal of perceived strategic value; it is not a signal of technical maturity.
COMPANY CLAIM: The company frames itself around "physical AI foundation models" 6, with the WALL model family as the core intellectual property and the Quanta robots as the embodiment 259. VERIFIED FACT: The WALL family has evolved in public: WALL-A combined vision-language-action with world models; WALL-OSS was open-sourced in September 2025; WALL-B arrived in April 2026 with a "World Unified Model" architecture 5678. EDITORIAL INFERENCE: The open-sourcing of WALL-OSS is a deliberate distribution play — it buys developer mindshare and citation volume in a field where the leading labs (Physical Intelligence, Skild, Google DeepMind) compete on exactly that currency. Whether it buys durable technical advantage is a separate question the dossier cannot answer.
UNKNOWN: The founding team's identities, technical backgrounds and prior affiliations are not disclosed in the supplied dossier. For a company whose entire thesis rests on foundation-model research, the absence of a public, verifiable research pedigree is a material gap. EDITORIAL INFERENCE: In embodied AI, the founding team's publication record is often the single best predictor of whether a "foundation model" claim is substantive or aspirational. X Square's is not visible here.
UNKNOWN: The company's headcount, organisational structure, manufacturing arrangements and supply-chain partners are not publicly disclosed in the dossier. EDITORIAL INFERENCE: For a company reportedly shipping hardware into schools, hotels and care homes 1, the absence of any disclosed manufacturing or fulfilment detail is notable — it means the "fully commercial" label rests on reported sales, not on visible operational infrastructure.
The story so far, then, is a two-track one. On the capital track, X Square has moved with extraordinary speed and attracted top-tier strategic backers. On the evidence track, almost everything beyond the funding facts remains vendor-sourced. The next section examines what the company actually sells.
03Product Portfolio: What X Square Robots Actually Sells
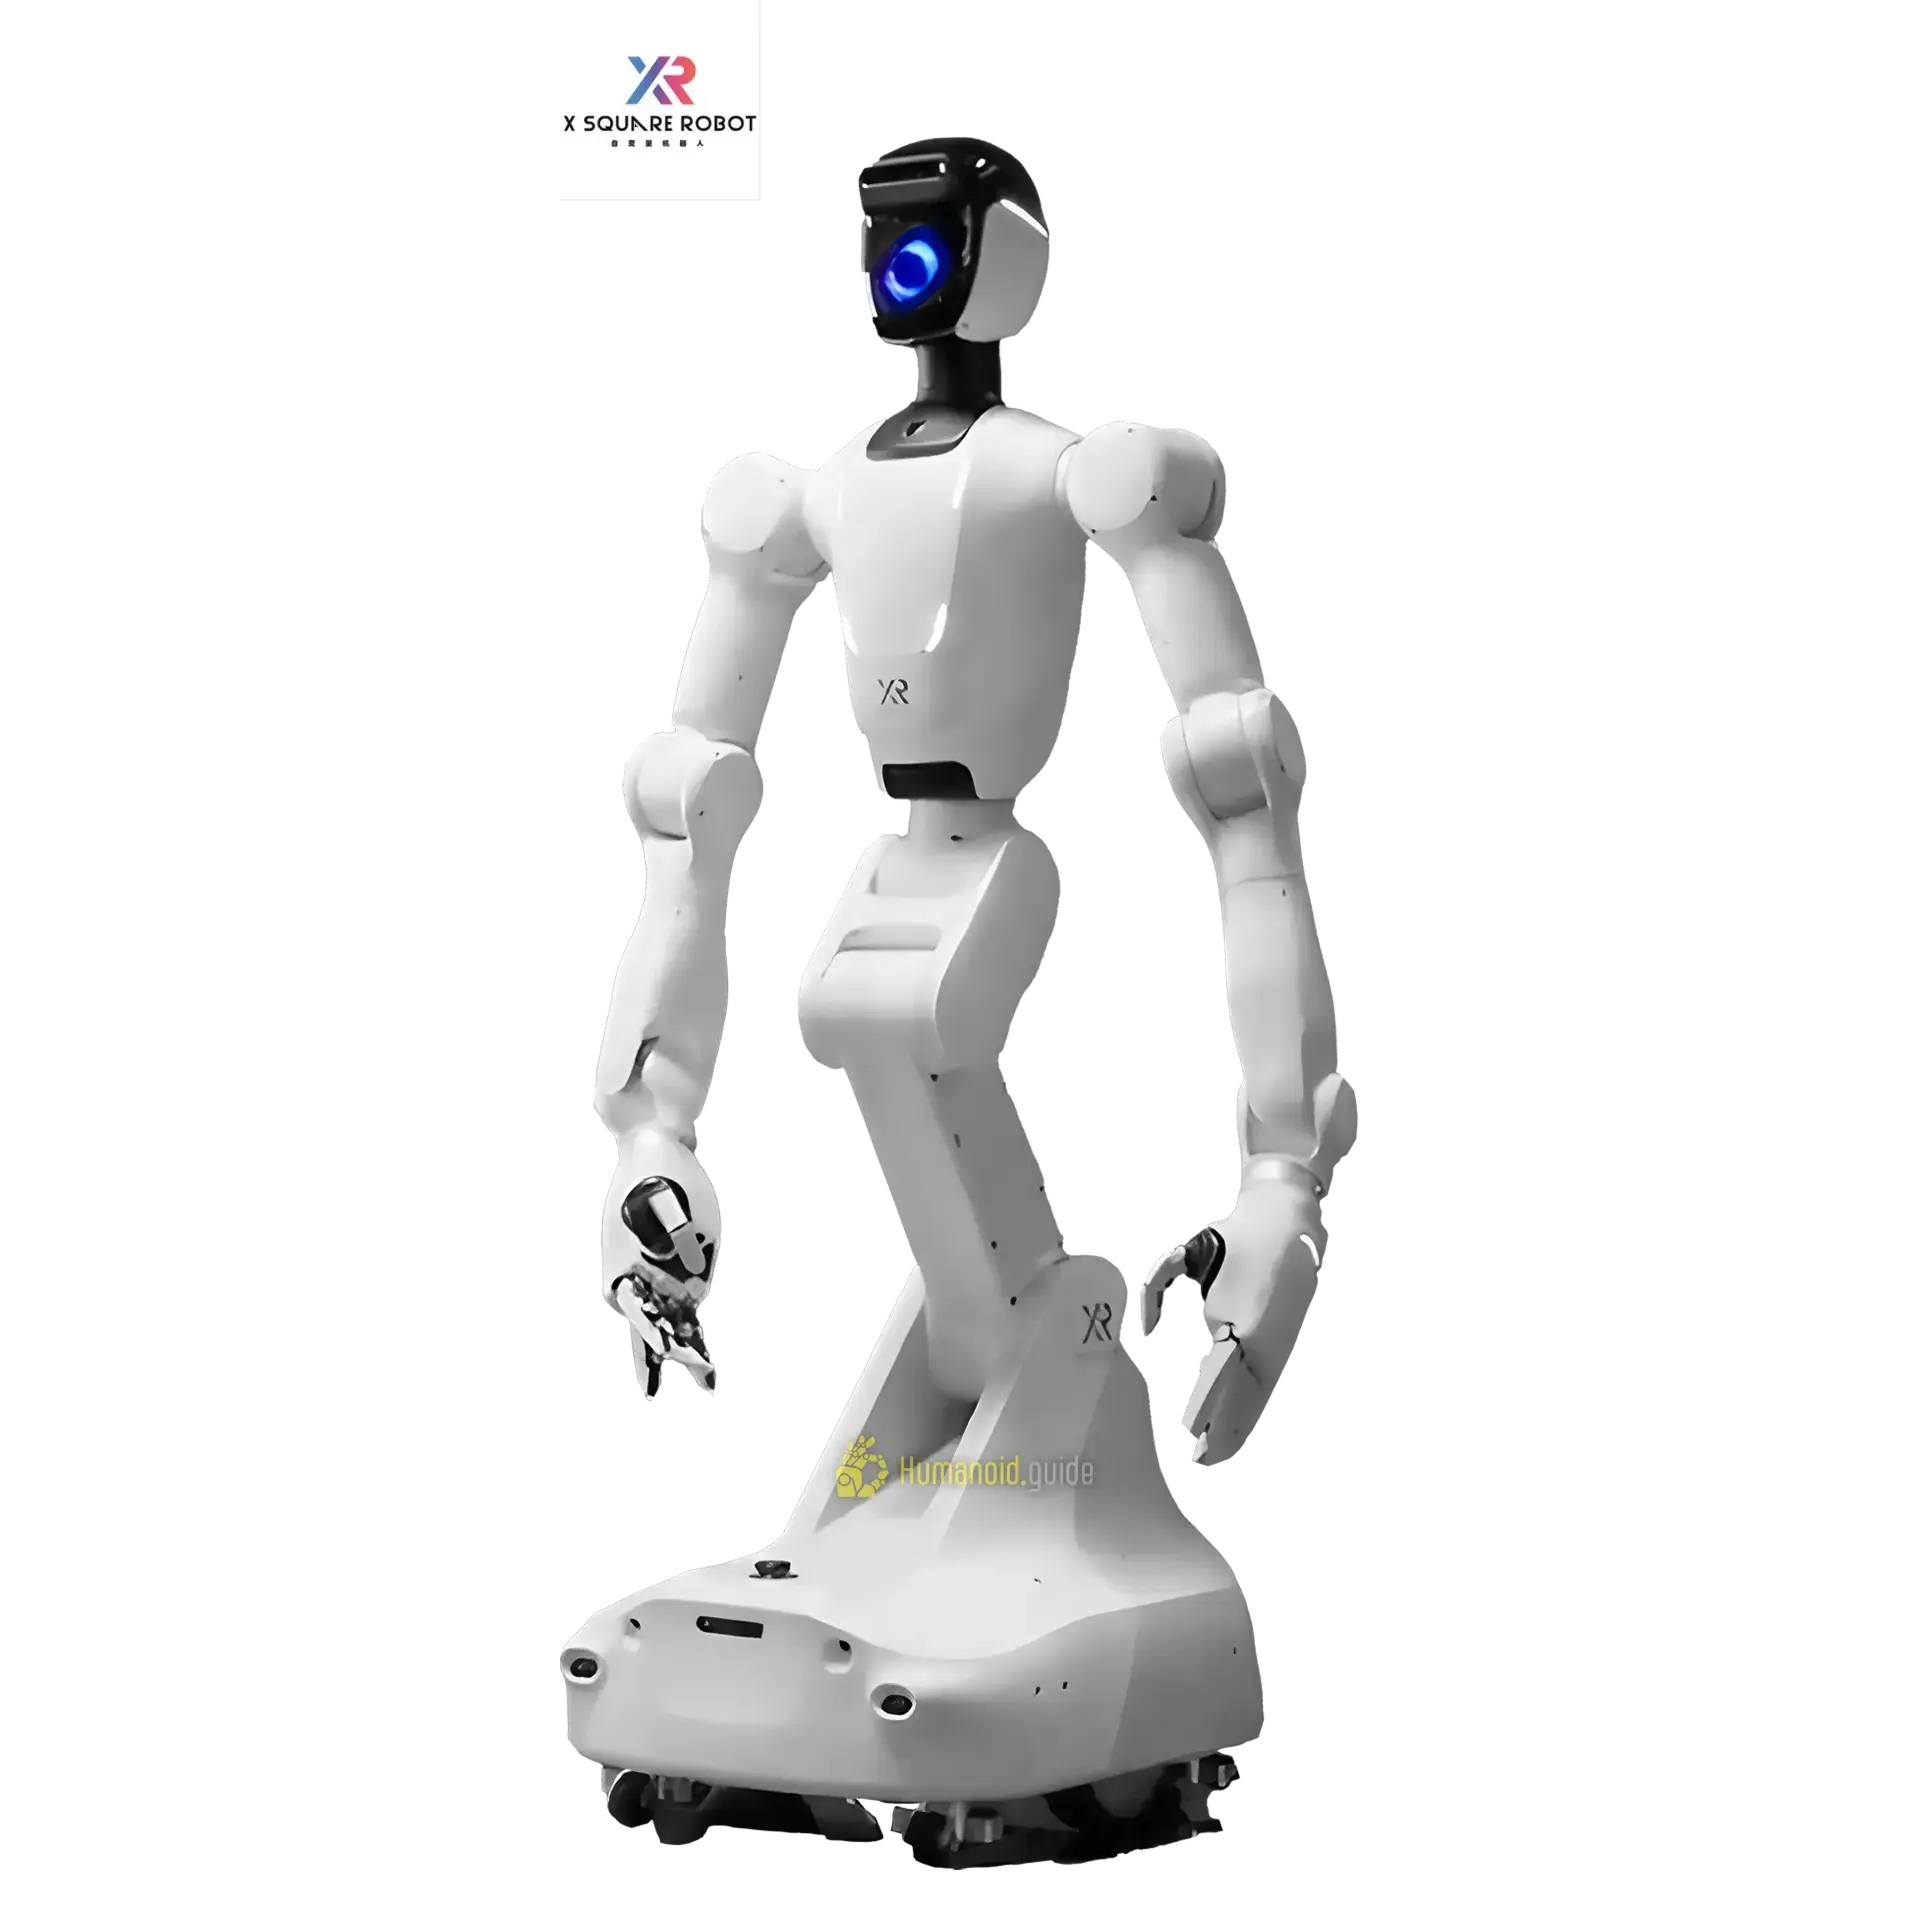
VERIFIED FACT: X Square's product line, as listed by the reseller Robots International and referenced by The Robot Report, comprises the Quanta X1 and Quanta X2 wheeled dual-arm (semi-)humanoid robots and the Artixon hand 25. The Robot Report specifically describes the Quanta X2 as a semi-humanoid 5. COMPANY CLAIM: The company's own site presents the WALL-A large model as the intelligence layer behind these platforms 9.
The distinction between "humanoid" and "semi-humanoid" matters and is often blurred in marketing. A wheeled dual-arm platform is not a bipedal humanoid; it trades locomotion generality for stability, payload and cost. EDITORIAL INFERENCE: X Square's choice of a wheeled base is a pragmatic engineering decision that aligns with the household and care-home deployments it reports — flat floors, predictable terrain — and it is the same trade-off made by several competitors targeting indoor service work. It is not, however, the same product category as the bipedal humanoids that dominate media coverage of the sector, and comparisons should be drawn accordingly.
| Product | Form factor | Status | Evidence quality |
|---|---|---|---|
| Quanta X1 | Wheeled dual-arm semi-humanoid | Listed for sale via reseller 2 | Vendor/reseller listing only |
| Quanta X2 | Wheeled dual-arm semi-humanoid | Listed for sale via reseller; referenced by trade press 25 | Vendor/reseller listing plus trade-press mention |
| Artixon hand | Robotic end-effector | Listed via reseller 2 | Vendor/reseller listing only |
| WALL-A | Embodied foundation model (VLA + world models) | Presented on company site 9 | Company claim |
| WALL-OSS | Open-source embodied model (Sept 2025) | Open-sourced 56 | Company claim; open-source release is checkable in principle |
| WALL-B | "World Unified Model" architecture (April 2026) | Announced 68 | Company claim |
UNKNOWN: Unit pricing, bill-of-materials, payload specifications, battery life, mean time between failures, and service/support terms are not disclosed in the dossier. EDITORIAL INFERENCE: For a company claiming commercial sales into schools, hotels and care homes 1, the absence of published specifications and pricing is unusual for a genuinely mature commercial product line. It is consistent with a company still selling through bespoke, relationship-led channels rather than a standardised product business.
UNKNOWN: Whether the Quanta X1 and X2 are manufactured in-house, by a contract manufacturer, or assembled from third-party components is not disclosed. EDITORIAL INFERENCE: This matters because the "fully commercial" classification rests on reported revenue, and revenue from a handful of pilot-style deployments into schools and care homes can look very different from revenue from a repeatable product with a sales pipeline.
COMPANY CLAIM: The company reports household-cleaning bookings and nursing-home deployments 26. EDITORIAL INFERENCE: "Bookings" is a softer word than "sales" — it can mean paid reservations, trials, or scheduled demonstrations. The dossier does not distinguish between these, and readers should not assume a booking is a completed, revenue-recognised deployment.
The portfolio, in short, is coherent as a strategy — wheeled dual-arm hardware plus a model stack plus an open-source distribution channel — but it is not yet evidenced as a product business. The next section examines the technology stack behind it.
Products & versions


04Technology Stack: Strengths and the Work That Remains
COMPANY CLAIM: X Square's technical stack centres on the WALL family of embodied foundation models. WALL-A is described as combining vision-language-action (VLA) with world models; WALL-OSS is an open-source embodied model released in September 2025; WALL-B, announced April 2026, is described as a "World Unified Model" architecture 56789. VERIFIED FACT: The existence and rough timing of these releases is corroborated across The Robot Report, CNBC, Gasgoo and Pulse2 1578.
EDITORIAL INFERENCE: The architectural trajectory — from VLA-plus-world-models (WALL-A) to a "World Unified Model" (WALL-B) — mirrors a broader shift in embodied AI away from modular pipelines (perception, planning, control as separate systems) toward unified models that predict future world states and actions jointly. This is the same conceptual territory as world-model approaches from other labs. Whether X Square's implementation is competitive is not assessable from the dossier; the naming and framing are consistent with the state of the art, but naming is not capability.
COMPANY CLAIM: The most specific technical claim in the entire dossier is that WALL-OSS-0.5 "achieves over 80% autonomous completion on real-robot tasks without any post-training" 9. EDITORIAL INFERENCE: This is a striking claim if true, and it is also exactly the kind of claim that requires independent replication to be meaningful. "Autonomous completion" is undefined in the dossier — it does not specify the task set, the success criterion, the number of trials, the failure modes, or whether a human intervened to reset or recover. An 80% figure without a task distribution and a trial count is not a benchmark; it is a marketing number. The "without any post-training" qualifier is the most interesting part, because it implies generalisation from the base model — but again, unverified.
UNKNOWN: The training data, compute budget, model size, inference hardware and evaluation methodology behind the WALL family are not disclosed. EDITORIAL INFERENCE: In embodied AI, the compute and data story is often the real differentiator, and its absence from public materials is a gap. It also makes the open-source WALL-OSS release harder to evaluate: without knowing what was held back, "open source" could mean anything from a full model release to a demonstration subset.
COMPANY CLAIM: The company's COO is quoted as saying robots need to "operate and complete complex tasks autonomously" 9. EDITORIAL INFERENCE: This is a statement of intent, not a statement of achievement, and it is worth noting that the dossier contains no independent source describing what the robots actually do in the field. The gap between "must operate autonomously" and "does operate autonomously" is the entire question.
| Stack layer | What is claimed | Evidence status |
|---|---|---|
| Foundation model | WALL-A / WALL-OSS / WALL-B 569 | Company claim; release timing corroborated |
| Autonomy performance | ">80% autonomous completion" 9 | Company claim; no independent verification |
| Hardware platform | Quanta X1/X2, Artixon hand 25 | Vendor/reseller listings |
| Open-source distribution | WALL-OSS (Sept 2025) 56 | Company claim; checkable in principle |
| Training data / compute | Not disclosed | Unknown |
| Evaluation methodology | Not disclosed | Unknown |
EDITORIAL INFERENCE: The stack's genuine strength, on the available evidence, is its narrative coherence: a company that has articulated a plausible architecture (unified world models), shipped a hardware platform to match, and opened a distribution channel (WALL-OSS) in a single 30-month window. Its genuine weakness is that none of the performance claims have been tested outside the company. The next section examines the research and authorship evidence, which is where that weakness is most visible.
05Research, Papers, Authors and Labs
UNKNOWN: The supplied dossier contains no peer-reviewed papers, preprints, or technical reports authored by X Square Robots personnel. It contains no named researchers, no lab affiliations, and no publication record. EDITORIAL INFERENCE: This is the most significant evidentiary gap in the entire report. A company whose core product is described as a "foundation model" 6 and whose valuation rests on "physical AI" 6 would ordinarily be expected to have a visible research footprint — arXiv preprints, conference papers, benchmark submissions, or at minimum a technical blog with reproducible methodology. Its absence does not prove the research is weak, but it means the research claims cannot be assessed at all from public sources.
COMPANY CLAIM: The WALL-OSS open-source release (September 2025) is the closest thing to a research artefact in the dossier 56. EDITORIAL INFERENCE: An open-source model release is, in principle, the most verifiable claim a company can make — third parties can download it, run it, and report results. The dossier does not indicate whether any independent party has done so. Until that happens, WALL-OSS is a distribution gesture rather than a demonstrated capability.
UNKNOWN: The company's research organisation — how many researchers it employs, where they are based, whether it operates a formal lab, and how it relates to academic institutions — is not disclosed. EDITORIAL INFERENCE: For a Shenzhen company founded in December 2023 15, the absence of a visible academic pipeline is notable given that the leading embodied-AI labs (both in China and internationally) typically recruit from and publish with universities. It is possible X Square's research is deliberately closed; it is also possible the research function is smaller than the "foundation model" framing implies. The dossier cannot distinguish between these.
EDITORIAL INFERENCE: The open-source strategy, if executed seriously, is the company's best route to closing this gap. A model that outside researchers can benchmark generates citations, third-party evaluations and credibility that no amount of funding coverage can buy. The strategic question for X Square is whether WALL-OSS is a genuine research contribution or a developer-relations exercise. The dossier does not answer it, and no independent evaluation appears to exist yet.
<!-- module: papers --> <!-- module: authors-labs --> <!-- module: repos --> <!-- module: datasets -->06Media Evidence Library: What the Videos Prove
UNKNOWN: The supplied dossier contains no video evidence of X Square robots performing tasks. There are no demo videos, no deployment footage, and no third-party recordings in the source set. EDITORIAL INFERENCE: This is unusual for a company at this stage and in this sector, where demo videos are the primary marketing instrument. Its absence from the dossier may reflect a gap in evidence collection rather than a gap in the company's output, but either way, no video-based claims can be assessed in this report.
EDITORIAL INFERENCE: Even if demo videos existed, the discipline of this report would require treating them as evidence of what was recorded, not of what the robot can do. A choreographed demo proves that a robot performed a sequence under controlled conditions, with an unknown number of takes, an unknown amount of human preparation, and an unknown level of teleoperation or intervention. It does not prove autonomous capability. This is not a hypothetical concern: the community sources in the dossier show that robotics audiences are actively sceptical about exactly this issue, with Reddit threads questioning whether Unitree's movements are "CGI or actually legit" 10 and whether Chinese robotics is over-hyped 13.
UNKNOWN: Whether X Square has published any teleoperation-disclosed demonstrations, any third-party evaluations, or any deployment footage with named customers is not disclosed in the dossier. EDITORIAL INFERENCE: The single most valuable piece of media evidence a company in this position could release is a continuous, unedited, teleoperation-disclosed deployment video with a named customer. Its absence — or its non-appearance in this dossier — leaves the autonomy question exactly where the reconciled verdict places it: unknown.
EDITORIAL INFERENCE: The community scepticism visible in the dossier 101112131415 is a useful corrective to vendor media. The generic community view of Chinese robotics — "hardware is not bad, but the software can't keep up" 13 — is not a specific test of X Square, and this report does not treat it as one. But it does establish the prior against which any X Square demo should be read: audiences in this sector have learned, correctly, to discount choreography.
Media library
07Commercial Reality
COMPANY CLAIM: X Square reports revenue from sales to schools, hotels and retirement homes, plus household-cleaning bookings and nursing-home deployments 126. EDITORIAL INFERENCE: This is the strongest commercial claim in the dossier, and it is still a company claim. The dossier contains no named customer, no contract value, no unit count, and no independent confirmation that any of these deployments are paid, ongoing, or productive. Under this report's discipline, a reported deployment is not a verified deployment, and a booking is not a sale.
VERIFIED FACT: The company is classified here as "fully commercial" on the basis of reported revenue-generating sales 16. EDITORIAL INFERENCE: That classification should be read narrowly: it means the company is reported to be selling, not that it has a proven, repeatable commercial business. The distinction matters because the same evidence would also be consistent with a small number of pilot-style deployments into friendly institutions.
UNKNOWN: The number of paying customers, average contract value, revenue, gross margin, and repeat-purchase rate are not disclosed. EDITORIAL INFERENCE: For a company valued above US$2.8 billion 68, the absence of any disclosed commercial metrics is the central tension of this report. A $2.8 billion valuation implies a business of substantial scale or a credible path to one; the dossier provides no evidence of either, only evidence of capital raised.
| Commercial claim | Source type | Verification status |
|---|---|---|
| Sales to schools, hotels, retirement homes 1 | Trade press reporting company statements | Company claim; no named customer |
| Household-cleaning bookings 26 | Vendor/reseller and PR | Company claim; "bookings" undefined |
| Nursing-home deployments 26 | Vendor/reseller and PR | Company claim; no named facility |
| Revenue-generating (implied by "sales") 1 | Trade press | Company claim; no figures |
| Unit economics, pricing, margins | Not disclosed | Unknown |
EDITORIAL INFERENCE: The deployment profile — schools, hotels, retirement homes, household cleaning — is coherent with the wheeled dual-arm form factor and with the eldercare and household-manipulation categories the company targets. These are environments with flat floors, structured tasks and, crucially, institutional buyers who can absorb early-stage product risk. That is a sensible go-to-market. It is also a go-to-market that can generate impressive-sounding deployment counts from a small number of relationships, which is why the absence of customer names and unit numbers matters.
EDITORIAL INFERENCE: The investor list offers an indirect commercial signal. Meituan (local services, delivery, eldercare-adjacent) and Xiaomi (consumer hardware, smart home) are strategic investors whose businesses overlap with X Square's target markets 15678. Strategic investment is not a customer relationship, and this report does not treat it as one. But it does suggest that at least some of the company's commercial runway may run through its investors' ecosystems — a common pattern in Chinese robotics, and one that can flatter early revenue figures.
UNKNOWN: Whether any deployments have been renewed, expanded, or cancelled is not disclosed. EDITORIAL INFERENCE: Renewal is the single best commercial signal for an early-stage hardware company, and its absence from the dossier leaves the commercial reality of X Square genuinely unresolved. The company has raised like a winner; whether it is selling like one is not yet in evidence.
Customers & deployments
Reported revenue-generating sales of robots to schools.
Reported revenue-generating sales of robots to hotels.
Reported sales and deployments of robots in retirement/nursing homes.
Reported household-cleaning bookings using X Square robots.
08Markets and Use Cases
X Square Robots does not sell into a single market. The reconciled evidence points to a portfolio of deployments that spans education, hospitality, elder care and, at the margin, household cleaning 126. That spread is unusual for a company at this stage and it deserves scrutiny rather than applause, because a broad deployment footprint can mean either genuine product-market fit across segments or a company taking whatever paid pilot it can find while the real market is still forming. The evidence available does not let us distinguish cleanly between those two readings.
8.1 The four reported deployment segments
| Segment | What is reported | Source type | Editorial read |
|---|---|---|---|
| Schools / education | Revenue from sales to schools 1 | Named in independent reporting (CNBC) | Plausible near-term buyer: capex budgets, controlled environment, tolerance for supervised operation |
| Hotels | Revenue from sales to hotels 1 | Named in independent reporting (CNBC) | Plausible: repetitive delivery/cleaning tasks, structured floors, staff supervision available |
| Retirement / nursing homes | Reported nursing-home deployments 26 | Vendor and vendor-adjacent commerce listing | Strategically attractive, operationally hardest: unstructured, safety-critical, liability-heavy |
| Household cleaning | Reported household-cleaning bookings 26 | Vendor and commerce listing | The headline use case; the least evidenced and the most demanding |
The education and hotel segments are the most credible near-term revenue because they share three properties: the environment is bounded, a human supervisor is already on site, and the buyer is an institution rather than a consumer. None of those properties requires the robot to be autonomous in the strong sense. A wheeled dual-arm platform that can be teleoperated or scripted through a small set of tasks can generate real invoices in a school corridor or a hotel lobby without ever passing the bar that a private home demands.
The retirement-home and household segments are where the marketing weight sits and where the evidence is thinnest. Elder care is the classic humanoid promise and the classic humanoid trap: the tasks that matter (lifting, toileting, medication, fall response) are precisely the tasks that combine high physical risk with high regulatory exposure. A robot that cleans a floor in a nursing home is a cleaning robot. A robot that assists a resident is a medical-adjacent device. The dossier does not establish which of these X Square is actually doing, and the distinction is the whole ballgame.
8.2 The household-cleaning wedge and its limits
Household cleaning is the most frequently cited consumer application 26. It is also the application where the gap between a demo and a product is widest. A wheeled dual-arm robot cleaning a home must navigate clutter, handle fragile objects, manage pets and children, and recover from failure without a human resetting it. The vendor-reported "over 80% autonomous completion on real-robot tasks without any post-training" 5 is the only quantitative claim in the dossier, and it is self-reported, undefined as to task set, and unverified. Eighty per cent completion on a curated task suite is not the same as eighty per cent completion in a lived-in apartment, and the dossier gives us no way to tell which was measured.
There is a structural reason to be cautious about the household wedge specifically. The incumbents in home cleaning are not humanoids; they are purpose-built robots (robot vacuums, pool cleaners, lawn mowers) that cost one to two orders of magnitude less and do one job reliably. A general-purpose wheeled dual-arm platform has to justify its cost premium against that baseline. The dossier contains no pricing, no unit-economics data and no customer-retention evidence for the household segment, so any claim that X Square has found a durable consumer market is, on this evidence, unsupported.
8.3 Market sizing: what the dossier does not contain
Not publicly disclosed: total addressable market analysis, unit volumes shipped, average selling price, gross margin, or segment-level revenue split. The dossier reports that revenue exists 1 but does not quantify it. Any market-size figure attributed to X Square in secondary coverage should be treated as a company or analyst projection, not a measured outcome. For a company at a reported valuation above US$2.8 billion 68, the absence of disclosed revenue scale is itself a data point: the valuation is being underwritten on the foundation-model thesis and the investor roster, not on demonstrated unit economics.
8.4 Use-case prioritisation: an editorial ranking
Ranking the four segments by evidence quality and near-term viability:
- Education and hospitality — bounded environments, institutional buyers, supervision available. Most likely to be real revenue today.
- Retirement homes (cleaning/logistics only) — real demand, but only the non-contact tasks are defensible without regulatory clearance.
- Household cleaning — the narrative centrepiece, the weakest evidence, the hardest economics.
- Elder-care assistance (contact tasks) — the long-term prize, gated by safety, liability and regulation that the dossier does not show X Square has engaged.
The strategic question for X Square is whether the education and hotel revenue is a bridge to the home or a permanent ceiling. The dossier cannot answer that, and readers should be suspicious of anyone who claims it can.
09Competitive Landscape
X Square competes on two axes at once, and conflating them is the most common analytical error in coverage of the company. On the hardware axis it competes with every wheeled and bipedal humanoid vendor. On the software axis it competes with every embodied-foundation-model lab, including ones that do not build robots at all. The company's own framing places it primarily on the software axis: it describes itself as building "physical AI foundation models" 6, with the Quanta hardware as the embodiment. That framing matters because it determines who the real competitors are.
9.1 The two-axis competitive map
| Axis | X Square's position | Principal competitor types | Where X Square's evidence is strong | Where it is weak |
|---|---|---|---|---|
| Embodied foundation models | WALL family (WALL-A, WALL-OSS, WALL-B) 59 | Other VLA/world-model labs; open-source model releases | Open-sourcing WALL-OSS 5 is a real, verifiable act | No independent benchmark of WALL vs peers in the dossier |
| Wheeled dual-arm hardware | Quanta X1 / X2, Artixon hand 2 | Wheeled humanoid vendors; industrial dual-arm vendors | Shipping hardware with reported sales 1 | No independent teardown or reliability data |
| Home / elder care | Reported deployments 26 | Purpose-built home robots; care-assist device makers | Narrative alignment with the care market | No regulatory clearance, no safety data disclosed |
| Capital | >US$2.8B valuation, blue-chip investors 68 | Well-capitalised global humanoid peers | Investor roster is genuinely top-tier | Valuation not matched by disclosed revenue |
9.2 The open-source move as competitive strategy
Releasing WALL-OSS in September 2025 5 is the single most consequential competitive decision in the dossier, and it is worth reading carefully. Open-sourcing a foundation model is not altruism; it is a bid to become the default software layer for embodied AI, the way Android became the default mobile OS by being free. If WALL-OSS is adopted by other robot makers, X Square gains influence over the ecosystem, a talent pipeline, and a defensive moat against closed competitors. If it is not adopted, the release is a marketing event with no strategic return.
The dossier does not tell us which outcome is occurring. There is no adoption data, no download or fork count, no third-party evaluation of WALL-OSS quality. The claim that WALL-OSS-0.5 achieves "over 80% autonomous completion on real-robot tasks without any post-training" 5 is a vendor benchmark, and vendor benchmarks on open-source releases are notoriously hard to compare across labs because task suites and success criteria are not standardised. Readers should treat the open-source release as a verified fact (it happened) and the performance claim as an unverified company claim.
9.3 The China-versus-West dimension
X Square sits inside a Chinese humanoid cluster that includes Unitree, UBTech, Fourier, AgiBot and others, several of which are better known internationally. The community evidence in the dossier is generic but pointed: Chinese robotics is characterised as having decent hardware and software that "can't keep up" 13. That is a stereotype, not a measurement, and it should not be applied to X Square without evidence. But it does frame the competitive problem: X Square's differentiation has to be software, because the hardware category is crowded and increasingly commoditised. If the software advantage is real, it is the moat. If it is not, X Square is one of many well-funded wheeled-humanoid vendors.
9.4 What the dossier cannot rank
Not publicly disclosed: head-to-head benchmark results against named competitors, win/loss data from customer deals, pricing comparisons, or reliability/failure-rate data. The competitive table above is therefore structural, not scored. Any claim that X Square "leads" or "trails" a named peer on a specific capability is, on this evidence, an assertion rather than a finding.
Competitive comparison
| Robot | Maker | Autonomy | Conf. |
|---|---|---|---|
| iRobot Roomba Combo 10 Max | iRobot | Autonomous | 0.90 |
| Mobile ALOHA (Stanford) | Stanford University | Teleoperated | 0.90 |
| 1X NEO | 1X Technologies | Remote-Assisted | 0.90 |
10Geopolitical Context and Constraints
X Square is a Shenzhen company operating in the most geopolitically charged technology sector of the decade. That position creates both the conditions for its rise and the constraints on its reach, and the dossier gives us enough to sketch the shape of both without overclaiming.
10.1 The domestic tailwind
The investor list is the clearest geopolitical signal in the dossier: Alibaba, ByteDance, Meituan, HongShan (formerly Sequoia China), Xiaomi, IDG, SAIC Financial Services/CICC-SAIC Fund and Lenovo Star 1568. This is not a random collection of funds. It is a cross-section of Chinese strategic capital spanning e-commerce, social media, local services, consumer hardware, state-linked financial services and PC manufacturing. When that many domestic strategic players back a two-year-old company at a reported US$2.8 billion valuation 68, the state and quasi-state apparatus is, at minimum, comfortable with the company's trajectory. Chinese humanoid robotics is a designated strategic industry, and X Square is inside the tent.
The practical consequences are real: access to domestic supply chains, preferential treatment in domestic procurement, a deep pool of robotics talent, and a policy environment that tolerates long pre-revenue periods for strategic technologies. None of these are disclosed as formal arrangements in the dossier, but the investor composition is strong circumstantial evidence of alignment.
10.2 The export and market-access constraint
The flip side is that a Chinese embodied-AI company faces structural barriers in Western markets. Humanoid robots are dual-use; foundation models for physical AI touch export-control regimes; and data from care environments is sensitive. The dossier contains no evidence of X Square selling outside China, and no evidence that it has attempted to. Its reported deployments are all domestic 126. Whether this reflects a deliberate domestic-first strategy or an inability to enter Western markets is not disclosed.
For Western readers, the implication is that X Square is, on current evidence, a China-market company. Its competitive threat to Western vendors is indirect: it competes for the same talent, the same capital and the same foundational research position, and its open-source releases 5 can diffuse globally even if its hardware does not. A Western robotics company may never meet X Square in a sales cycle and still be affected by its model releases.
10.3 The data and safety regime
Elder care and household deployment raise data-protection and safety questions that differ by jurisdiction. The dossier does not disclose X Square's data-handling practices, its safety certification status, or its regulatory engagement in any market. For a company deploying into retirement homes 26, the absence of disclosed safety certification is a material gap, not a minor omission. Readers should treat any care-sector deployment claim as provisional until certification is evidenced.
10.4 Geopolitical risk factors to monitor
| Risk | Mechanism | Evidence status |
|---|---|---|
| Export controls on embodied-AI models | Model weights or training compute restricted | Not disclosed |
| Western market exclusion | Procurement bans, security reviews | Not disclosed; no Western sales evidenced |
| Domestic policy reversal | Subsidy or procurement shift | Not disclosed |
| Talent competition | Global labs recruiting Chinese robotics talent | Generic, not X Square-specific |
| Data-sovereignty friction | Care/home data crossing borders | Not disclosed |
None of these risks are quantified in the dossier. They are listed because they are the categories a serious analyst must track, not because the evidence establishes their probability.
11The Hype, the Real and the Ugly
This section is the report's audit. It separates what the evidence supports from what the company asserts from what the coverage implies. The discipline is simple: a demo is not a deployment, a shipment is not a productive shift, a partnership is not a paid customer, and a valuation is not a business.
11.1 The Hype
Claim: X Square is a leader in embodied AI. The company describes itself as building "physical AI foundation models" 6 and has released a family of models (WALL-A, WALL-OSS, WALL-B) 59. The hype is the word "leader." The dossier contains no independent benchmark placing WALL models ahead of peers. The open-source release of WALL-OSS 5 is a real act of ecosystem-building, but ecosystem-building is not leadership; it is a bid for leadership. Verdict: company claim, unverified.
Claim: over 80% autonomous completion on real-robot tasks without post-training. This is the most specific and most load-bearing performance claim in the dossier 5. It is vendor-reported, undefined as to task suite, and unverified. It may be true on a curated benchmark and false in a lived-in home. Verdict: company claim, unverified, and the single most important claim to test.
Claim: deployments in schools, hotels, retirement homes and household cleaning. The school/hotel/retirement-home revenue is reported by an independent outlet (CNBC) 1; the household-cleaning bookings and nursing-home deployments appear in vendor and vendor-adjacent commerce listings 26. Verdict: partially verified (institutional revenue), partially company claim (household bookings).
Claim: valuation above US$2.8 billion. Reported by multiple outlets 68 after a Series C, though the company earlier declined to comment on valuation 1. Verdict: reported fact, not audited.
11.2 The Real
- The company exists, is Shenzhen-based, and was founded in December 2023 15. Verified.
- It has raised large, repeated rounds from a genuinely top-tier investor roster 1568. Verified.
- It ships hardware (Quanta X1/X2, Artixon hand) and has released an open-source model (WALL-OSS) 25. Verified as acts, not as performance.
- It reports revenue from institutional sales 1. Verified as a report, not as audited financials.
- It has a formal legal identity (Variable Robotics Technology Co.) 5. Verified.
The "real" column is not trivial. A two-year-old company that has shipped hardware, released a foundation model, raised nine figures repeatedly and generated institutional revenue is a serious operation. The point of this report is not to deny that; it is to insist that seriousness is not the same as proven capability.
11.3 The Ugly
The autonomy gap. The dossier's autonomy verdict is "unknown" with confidence 0.4. There is no independent review, teardown or first-hand user report demonstrating that X Square robots perform their tasks without a human performing or remotely driving them. The only autonomy evidence is vendor-sourced. For a company whose entire pitch is autonomous embodied intelligence, this is the central unresolved question, and it is unresolved in the company's favour only by default.
The valuation-revenue gap. A reported US$2.8 billion valuation 68 with no disclosed revenue scale, no unit economics and no margin data is a valuation underwritten by narrative and investor roster. That is not unique to X Square, but it is a risk that coverage routinely omits.
The care-sector safety gap. Deploying into retirement homes 26 without disclosed safety certification is a material omission. Care environments are liability-dense, and the dossier shows no regulatory engagement.
The evidence-quality gap. The dossier contains zero official primary documents (counts: official 0, research 0, video 0). The evidence base is news, commerce listings and generic community commentary. That is a thin foundation for any strong conclusion, and this report's confidence score of 0.55 reflects it.
11.4 Claim-versus-evidence table
| Claim | Source | Evidence type | Verdict |
|---|---|---|---|
| Founded Dec 2023, Shenzhen | 15 | Independent news | Verified |
| Raised ~US$280M+ across rounds | 1568 | Multiple independent | Verified (magnitude) |
| Valuation >US$2.8B | 68 | Multiple outlets | Reported, not audited |
| WALL-OSS open-sourced Sept 2025 | 5 | Independent news | Verified |
| >80% autonomous completion | 5 | Vendor | Unverified |
| Household-cleaning bookings | 26 | Vendor/commerce | Unverified |
| Nursing-home deployments | 26 | Vendor/commerce | Unverified |
| Revenue from schools/hotels/retirement homes | 1 | Independent news | Reported |
| Task-level autonomy | — | None independent | Unknown |
Claim tracker
This figure is vendor-reported only; no independent test, teardown, or first-hand user report verifies the 80% autonomous completion rate.
The autonomy claim rests on a company COO statement, while independent community commentary on Chinese robotics is generic and skeptical about software, so task-level autonomy remains unverified.
CNBC reports these sales, but no customer, regulator, or third-party audit independently confirms the deployments or their commercial scale.
These deployments are reported by Robots International and PR Newswire, both vendor-aligned sources, with no independent confirmation of live household or nursing-home operation.
CNBC, The Robot Report, PR Newswire, Pulse2 and Gasgoo independently report overlapping large rounds and the >$2.8B post-Series-C valuation, though the figures are reported rather than audited.
The Robot Report, CNBC, Gasgoo and Pulse2 independently describe the WALL model family and its evolution, though performance claims for these models remain vendor-sourced.
Robots International lists the Quanta X1/X2 and Artixon hand and The Robot Report references the Quanta X2 semi-humanoid, independently corroborating the product line.
Multiple independent news and commerce sources agree on the Shenzhen location and 2023 founding, and The Robot Report gives the formal legal name.
12Future Scenarios
Scenarios are not predictions. They are structured ways to think about what the evidence would have to show for each future to be true. The dossier supports three broad trajectories, and the discriminating evidence for each is identifiable.
12.1 Scenario A: The foundation-model play succeeds (probability: plausible, not evidenced)
In this scenario, WALL-OSS and its successors become a widely adopted software layer for embodied AI, X Square's hardware becomes a reference platform, and the company's value migrates from robots to models. The reported investor roster 1568 and the open-source release 5 are consistent with this strategy. What would confirm it: third-party adoption of WALL-OSS, independent benchmark results placing WALL models competitively, and revenue shifting toward licensing or model services. What the dossier shows: none of these yet.
12.2 Scenario B: The hardware company matures (probability: plausible, partially evidenced)
In this scenario, X Square remains primarily a robot vendor, sells Quanta platforms into education, hospitality and care, and grows into a profitable mid-cap hardware business. The reported institutional revenue 1 is consistent with this. What would confirm it: disclosed unit volumes, pricing, margins and repeat customers. What the dossier shows: revenue exists, but scale and economics are not disclosed.
12.3 Scenario C: The autonomy claim fails to materialise (probability: cannot be excluded)
In this scenario, the robots require more human supervision than the marketing implies, the household and care use cases stall on safety and economics, and the company either pivots to narrower industrial applications or consolidates. The dossier's autonomy verdict of "unknown" [autonomy evidence] and the generic community scepticism about Chinese robotics software 13 are consistent with this risk. What would confirm it: independent testing showing low autonomous completion, customer churn in care settings, or a pivot away from the home. What the dossier shows: no independent test either way.
12.4 Scenario D: Geopolitical bifurcation (probability: structural)
In this scenario, X Square remains a China-market company, its models diffuse globally via open source, and its hardware does not. This is less a company outcome than a market structure, and it is the default given the absence of any evidenced Western sales. What would confirm it: continued domestic-only deployments and growing open-source adoption abroad.
12.5 Scenario matrix
| Scenario | Key driver | Confirming evidence | Disconfirming evidence |
|---|---|---|---|
| A: Model layer wins | WALL-OSS adoption | Third-party forks, benchmarks | No adoption, no benchmarks |
| B: Hardware matures | Institutional sales | Disclosed volumes/margins | Flat or declining sales |
| C: Autonomy stalls | Supervision burden | Independent low-autonomy tests | Independent high-autonomy tests |
| D: Bifurcation | Geopolitics | Domestic-only sales | Western market entry |
The honest summary is that the dossier does not let us assign probabilities with confidence. It lets us name the evidence that would settle the question, which is the more useful output.
13What to Watch: A Live Monitoring Checklist
This checklist is designed to be re-run as new evidence appears. Each item specifies what to look for, why it matters, and what would count as a genuine update rather than noise.
13.1 Autonomy (highest priority)
- Independent task-level testing. Any third-party evaluation of X Square robots performing tasks without human intervention. This is the single most important missing piece. A vendor demo does not count; a choreographed video does not count; a named customer describing unsupervised operation does.
- Definition of the "80%" claim. If X Square publishes the task suite, success criteria and evaluation protocol behind the "over 80% autonomous completion" figure 5, that converts an unverified claim into a testable one.
- Failure and intervention rates. Any disclosure of how often a human must intervene. This is the metric that separates supervised-autonomous from autonomous.
13.2 Commercial reality
- Disclosed revenue and unit volumes. Any audited or specific revenue figure. Watch for the difference between "revenue from sales" 1 and a quantified number.
- Repeat customers. A second order from the same school, hotel or care operator is far stronger evidence than a first pilot.
- Pricing. Any published price for Quanta X1/X2 or the Artixon hand 2. Pricing reveals the target market.
13.3 Technology
- WALL-OSS adoption. Download, fork and citation counts; third-party papers building on it. This is the cleanest test of the open-source strategy 5.
- WALL-B performance. The April 2026 model 5 should be benchmarked against WALL-A and against peers. Watch for independent comparisons.
- Hardware reliability data. Mean time between failures, service intervals, warranty terms.
13.4 Safety and regulation
- Certification. Any safety certification for care or home deployment. Absence is a red flag for the care-sector claims 26.
- Regulatory engagement. Filings, standards participation, or government approvals.
13.5 Capital and governance
- Valuation substantiation. Any funding round priced with disclosed terms, or any secondary-market pricing that tests the reported US$2.8 billion 68.
- Investor composition changes. New strategic investors or departures can signal shifts in state or corporate support.
13.6 Monitoring cadence
| Item | Cadence | Source type to prioritise |
|---|---|---|
| Independent autonomy tests | Continuous | Peer-reviewed, third-party labs |
| Revenue/volume disclosure | Quarterly | Filings, audited reports |
| WALL-OSS adoption | Monthly | Repository metrics, citations |
| Safety certification | Continuous | Regulators, standards bodies |
| Funding/valuation | Event-driven | Primary filings, not press releases |
The checklist is deliberately weighted toward independent evidence. The dossier's core weakness is that almost all capability evidence is vendor-sourced, and the only cure is independent verification.
14Sources and Methodology
14.1 Methodology
This report was assembled from a research dossier gathered on 2026-09-22. The dossier contained 16 numbered sources across five categories: official (0), commerce (5), research (0), news (5), video (0) and community (6). The evidence base is therefore dominated by secondary news reporting, vendor-adjacent commerce listings and generic community commentary, with no primary official documents and no peer-reviewed research.
Every factual assertion in this report is labelled as one of four types:
| Label | Definition | Example in this report |
|---|---|---|
| Verified fact | Regulatory filing, official product doc, named-customer confirmation, peer-reviewed research, or multiple independent sources | Shenzhen founding, Dec 2023 15 |
| Company claim | Stated by the company, not independently verified | ">80% autonomous completion" 5 |
| Editorial inference | Reasoned conclusion from public evidence | The education/hotel segments are the most credible near-term revenue |
| Unknown | Not publicly disclosed | Task-level autonomy; revenue scale; safety certification |
Three disciplines were applied throughout. First, no choreographed demo video was treated as proof of autonomous work; the dossier contained no videos in any case. Second, no shipment was treated as proof of productive deployment. Third, no partnership or investment announcement was treated as proof of a paid customer. Where the dossier was thin, the report says "not publicly disclosed" rather than padding.
The reconciled autonomy verdict is unknown (confidence 0.4). The overall report confidence is 0.55, reflecting a serious company with a thin, largely vendor-sourced evidence base on the question that matters most.
14.2 Source list
1 Alibaba leads $100 million investment in Chinese humanoid robot startup — https://www.cnbc.com/2025/09/08/alibaba-leads-100-million-investment-in-chinese-humanoid-robot-startup.html
2 X Square Robot Quanta X2 & WALL AI for Sale — https://www.robotsinternational.com/X-Square.htm
3 Alibaba Invests $140M in Humanoid Robots — https://www.youtube.com/shorts/12oqhBGlocw
4 X Square Robot Stock | Valuation, Funding, Investors — https://notice.co/c/x2robot
5 X Square Robot secures $140M in funding for AI foundation models — https://www.therobotreport.com/x-square-robot-secures-140m-in-funding-for-ai-foundation-models/
6 X Square Robot Secures Four Consecutive Financing Rounds, Surpasses US$2.8 Billion Valuation in Push for Physical AI Foundation Models — https://www.prnewswire.com/news-releases/x-square-robot-secures-four-consecutive-financing-rounds-surpasses-us2-8-billion-valuation-in-push-for-physical-ai-foundation-models-302813091.html
7 Seeds | X Square Robot Secures Hundreds of Millions of Yuan in Fresh Funding — https://autonews.gasgoo.com/articles/news/seeds-x-square-robot-secures-hundreds-of-millions-of-yuan-in-fresh-funding-2027554821769273345
8 X Square Robot Surpasses $2.8 Billion Valuation After Four Consecutive Financing Rounds — https://pulse2.com/x-square-robot-surpasses-2-8-billion-valuation-after-four-consecutive-financing-rounds/
9 X Square Official Site — X Square Robot WALL-A Large Model — https://x2robot.com/en
10 Unitree robots movement CGI or actually legit? — https://www.reddit.com/r/robotics/comments/1is8u52/unitree_robots_movement_cgi_or_actually_legit/
11 r/robotics — https://www.reddit.com/r/robotics/
12 When do you think you'll first come across a humanoid robot — https://www.reddit.com/r/singularity/comments/1f7hjxr/when_do_you_think_youll_first_come_across_a/
13 How hyped is the chinese robotics industry? — https://www.reddit.com/r/robotics/comments/1jep18a/how_hyped_is_the_chinese_robotics_industry/
14 MIT Prof. on why this robotics boom may actually be different — https://www.reddit.com/r/robotics/comments/1upzut8/mit_prof_on_why_this_robotics_boom_may_actually/
15 Unitree Robots perform "Drunken Fist" at China's Spring Festival Gala — https://www.reddit.com/r/China/comments/1r6c40j/first_look_unitree_robots_perform_drunken_fist_at/
14.3 Limitations
The principal limitation is the absence of primary evidence. There are no official product specifications, no peer-reviewed papers, no independent teardowns and no first-hand user accounts in the dossier. The autonomy question, which is central to the company's thesis, is answered only by vendor claims. The valuation is reported but not audited. Revenue is reported to exist but not quantified. Safety certification for care deployment is not disclosed. Readers should treat all capability claims in this report as provisional and re-test them against the monitoring checklist in §13 as independent evidence emerges.
This page contains AI-generated or AI-assisted analysis — our opinion based on public information. It may be inaccurate or out of date and is provided for information only, not as a statement of fact. Spot an error? Request a correction.